 Android & iPhone
CARITY VOLUNTARY 15 SEPTEMBER: What has been changed to the new version and what are the obstacles?
Jinse Finance
Just now
Todju, the gold fortune.
Update: On September 14th, US time, Trump agreed on a new ethical clause for the Clarity Act. Encrypted journalist Eleanor Terrett wrote that Republican members of the United States Senate published a new version of the CLARITY Act incorporating the revised ethical proposal agreed to by Trump, and synchronized with the blockchain Regulatory Determination Act (BRCA), stabilization gains and so-called "Ag Clauses".
Polymarket data show that the chance that the Clarity Act will pass into law in 2026 has increased significantly from 14 per cent to 33 per cent.
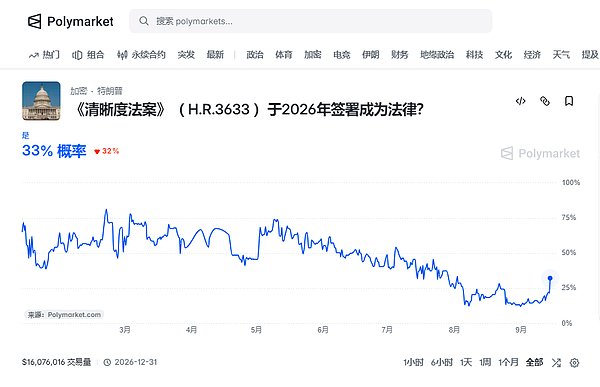
The encryption market also reacted, with the BTC rising slightly from $76,000 to $77,800 and ETH breaking $2,500.
Summary:The United States Senate will hold a critical vote on the CLARITY Act's closure procedure at 2:15 p.m. Eastern US time on 15 September. Why is this vote so important? What changes have been made to the new version of the bill? What are the main obstacles facing the CLARITY Act?
I. On 15 September?
1. Procedure for closing the debate
The United States Senate did not vote directly on 15 September on the final adoption or non-adoption of the CLARITY Act, but first faced a more critical procedural juncture — an end to the debate.
The adjournment process is an attempt by the Senate to end the unlimited debate on a bill and to move it into a follow-up procedure. The rules of the United States Senate determine that most legislative matters need to be supported by three fifths, 60 senators, in order to pass the closure procedure.
If the closing of the debate is supported by 60 votes or more, the Senate will still have to deal with remaining proceedings, including the stages of debate, amendments and eventual adoption; if it does not reach 60 votes, the bill will face great difficulties in moving forward.
Reuters has pointed out that the Senate leadership has made the 15 September procedural vote an important point in testing support for the bill, and that the possibility of completing legislation this year will be significantly reduced when the mid-November elections approach and the remaining Senate days are limited.
If 15 September fails, what happens?
The most immediate impact is that the CLARITY Act will lose political momentum to move forward rapidly, making it very difficult for the bill to complete legislation by 2026. In particular, the United States House of Representatives has shortened its September working arrangements and is approaching the mid-November elections.
If it is adopted on 15 September, how far will it go?
Even if the proceedings for the closure of the debate on 15 September were successful, the CLARITY Act did not become law on that day. Following this may still be a significant point in time, with the adoption of the procedure for the closing of the debate, the Senate continuing to deal with bills and possible amendments, the Senate holding a final vote, coordination between the texts of the two houses, the adoption of a final agreed version by both chambers, and the presentation of the President for signature.
II. What changes have been made to the new version
New rules for “non-centreized financial transactions agreements”
The new version includes the formulation of new rules for “non-centreized financial transaction agreements”, describing it as “an individual or group that directly or indirectly controls or substantially alters the functions, operations or consensus or protocol rules of a decentrized financial transaction agreement by any contract, arrangement, understanding, relationship or other means”.
If a project ostensibly uses smart contracts, non-trust structures or decentrized names but actually has the core functions of a company, team or particular individual who can continuously control an agreement, it may not be able to enjoy exemptions from the genuine decentrization agreement.
This change is actually addressing a very difficult issue in the previous CLARITY Act: if the law takes too broad an exemption from DeFi, then the central platform may be able to package itself through technical structures and define itself as a DeFi agreement, thus avoiding registration and regulation. If the regulatory scope is too wide, it could also incorporate real open source software developers, DAOs, and decentrized agreements into traditional financial regulatory systems.
The “de-centreization” agreement may be incorporated into the CFTC regulation
As currently drafted, such agreements would not simply rely on DeFi attributes to circumvent regulation and might require registration with the United States Commodity Futures Trading Commission (CFTC).
Democrat parliamentarians have been concerned that, if the CLARITY Act were to impose an overly broad exemption on DeFi, some of the large central trading platforms could escape regulation through technical packaging. The new version therefore distinguishes between “real Defi” and “agreements with de facto control” by introducing the concept of a “decentre financial transaction agreement.”
DeFi clauses have been expressly narrowed to “ spot and cash digital commodity transactions”
The updated version also makes it clear that the DeFi clause applies only to “cash and cash digital commodity transactions.” The Republican Senator Cynthia Loomis of Wyoming states that this is intended to address tribal government concerns about the possible impact of CLARISTY Act on forecast markets.
4. How credit unions conduct encryption operations
Unlike commercial banks, credit unions are usually member-owned and not-for-profit financial institutions that have a role in the United States financial system to serve individuals, communities and certain specific groups.
While previously CLARITY Act, when discussing the involvement of banks in digital asset operations, market concerns were concentrated mainly on large commercial banks and stable money distributors, in fact credit unions are also included in a significant number of United States financial institutions. The new version further clarifies the regulatory boundaries for the participation of credit unions in digital asset activities.
III. Main remaining obstacles to the CARITY Act
1.60 vote threshold
The most realistic question for the CLARTY Act is whether 60 votes can be obtained in the Senate. The Republican party currently has 53 seats in the Senate, and even if all 53 Republican senators are in favour, it will still require at least seven Democrats or independent senators to vote in favour of the 60-vote threshold needed to close the debate.
2. Ethical provisions
One of the central reasons for the Democratic Party’s current opposition to CLARITY Act is that President Toran has spread his family’s commercial interests in encryption. Democrat parliamentarians believe that there is a clear risk of conflict of interest if the President and his family continue to derive huge gains from crypto assets, while the executive branch is responsible for developing and implementing policies to regulate encryption.
The Democratic Committee of the Senate Banking Commission has previously continued to exert pressure on this issue. There are still large gaps in the ethical provisions contained in existing texts that do not effectively prevent Trump from continuing to benefit from existing or new encryption operations.
The Republican side, although it has incorporated the relevant ethical restrictions in the text, is still not convinced that it is strong enough. Therefore, a new compromise between the two sides on the question of placing government officials in encryption is likely to have a direct impact on whether or not the Democratic Party is willing to provide critical procedural support.
3. DeFi regulates borders
The Republican Party wishes to adopt legislation that will provide clear protection for genuinely decentrized agreements, developers and software innovations, avoiding the responsibility of traditional financial institutions for those who develop open source codes because they are ultimately used by users; the Democrats and regulators fear that if DeFi were too wide an exemption, some trading platforms which are actually controlled by companies or individuals might circumvent regulation through a “decenterized” technical framework.
Thus, the new version adds the concept of a “non-centreized financial transaction agreement.” “If an individual or group is able to control, directly or indirectly, substantial changes in the functions, operations, consensus or rules of the relevant transaction agreement, then the agreement may be considered “non-centralized” and subject to CFTC supervision.” It is not possible, however, to define “substantive control”.
4. Stabilizing currency gains
The core dispute is whether stabilizing the issuer and related platforms can provide benefits to users, or share them with the proceeds of stable currency reserves?
Some Democrat parliamentarians fear that, if the rules are too loose, large encryption platforms may gain a similar advantage over bank deposits, while weakening the competitiveness of traditional banking systems. For the encryption industry, for example, too tight legal restrictions on securitizing currency gains could also weaken stable currency business models in payments, transactions, and chain finance.
The banking sector is concerned that the new regulatory framework for digital assets may give encryption platforms more liberal regulatory conditions than traditional financial institutions. In particular, operations such as currency stabilization, hosting, and digital asset transactions, banks may face a loss of deposits and a changing competitive environment if large amounts of money flow from traditional banking systems to encrypted platforms in the future.
More content to viewThe Bank wants our money: the truth behind the CLARITY Act.
IV. What does it mean if the CLARITY Act is adopted?
United States encryption controls move from “enforcement regulation” to “legislative control”
The central long-standing problem facing the United States encryption industry over the past few years has been the lack of clarity about regulatory boundaries.
In particular, between SEC and CFTC, there has been a continuing controversy as to which digital assets are securities, which commodities and which transactions should be regulated.
In March this year, the SEC and the CFTC have been released jointly.Statement• Categorize digital goods, digital collections, digital tools, stable currency and digital securities, among others, and make it clear that some non-securitized crypto assets may fall under the purview of the CFTC. The SEC also makes it clear that this interpretation is providing a basis for Congress to move forward with comprehensive market structure legislation. If the CLARITY Act is passed, the United States will for the first time have this regulatory framework in federal law.
2. Clarifying the scope of authority of the SEC and the CTC
A large number of digital assets, as well as spot markets, will fall within the CFTC regulatory framework, while the SEC is primarily responsible for areas such as digital securities. If designated as securities by the SEC, the platform may involve a whole range of regulatory requirements, such as stock exchanges, brokers, clearing houses, etc.; if it is commodities, it will mainly enter the CFTC regulatory system.
The encryption industry is expecting that the CLARITY Act will provide a clearer legal basis for encryption enterprises in the United States.
3. Harnessing American encryption
Previously, because of unclear regulatory rules, some encryption projects chose to register, finance, or operate outside the United States. Trump had previously expressed his intention to make the United States a city of encryption, and the advent of CLARITY Act would help the United States to regain its role as the leading regulatory and innovation centre for the global encryption industry.
4. Possible clearer legal protection for DeFi
If the final version retained special arrangements for genuine de-centreization agreements, the developers, DAOs, open source agreements and non-trusted DeFi projects would be given clearer legal boundaries than in the past.
5. Encrypted tracks for accelerated access to traditional finance
If the market structure bill establishes regulatory subjects and operational boundaries, it makes it easier for traditional financial institutions to calculate the costs of entering the encrypted market. Under the established regulatory framework, banks, voucher dealers, asset management agencies may be able to accelerate access to the encrypted market.
V. Views of the industry
United States Treasury Secretary Scott Besent: “In July this year, I called on the Senate to move forward with the CARITY Act — a bill designed to establish a comprehensive regulatory framework for digital assets and to enhance our ability to prevent outlaws from using these critical technologies. When the Senate adjourned in August, I strongly urged all to remain at the negotiating table to agree on moving forward on the motion and to continue with the legislative process. Failure to do so will send a worrying signal to our allies and adversaries that the United States is not willing to play a leading role in the future development of digital assets, nor is it willing to abandon tools to strengthen national security and combat the misuse of digital assets. I'm sorry.
Paul Atkins, who was nominated to chair the SEC, and Michael Selig, who is president of CFTC, said that digital asset regulation would continue if the CIA Act did not move forward this year.
United States Senator Loomis: If a congressman fails to reach an agreement and submit the bill to the President for signature, the next chance of adoption may be in 2030.
Coinbase CEO Brian Armstrong: Even if the CLARITY Act was not adopted, the result would still be “good” and the United States Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) were ready to introduce legislation on cryptocurrency.
CLARISTY Act, the original sponsor of the House of Representatives, Chairman of the Chamber of Deputies Financial Services Committee and Congressman French Hill of Arkansas: believed that the Senate majority leader, John Tunn, would be able to obtain sufficient votes for the bill to be passed in a procedural vote on the afternoon of 15 September.
Kristin Smith, President of the Institute for Policy Studies in Solana: “Democrats can hardly vote in favour unless they get a moral clause as their core. This remains the most critical part of the whole matter.”
 6

Declaration: This is a gold original, the copyright is a gold one and cannot be reproduced without authorization. A copy of this article must be downloaded from an agreed-upon medium with the indication "Source: Gold Book", for which the offender will be held liable under the law.
This information is not a financial investment proposal.
 Save


- Pantera's latest status report on monetization.
- What game is AAVE playing next?
- US SEC issues an update of the crypto asset FAQ to add a new issuer's currency buyback definition
- QNT surged over 300% a week, currency deposits infiltrated the core of the United States banking system?
- Vitalik's latest post: The Ether Workshop will become a password-based world computer.
24-hour text
 Eight hidden details of Anthropic's book.
GenAI Summit
 Bitcoin goes into shock and waits for a new catalyst?
Knight of the Zone Chain.
 How did the harvest line at the Meme Factory come out of the water, Robinwood Chain?
Chain catcher ChainCatcher
- Seeking coverage
- Jinse Finance AppiOS & Android
- Community
Telegram - Feedback
- Back to Top
- Back to Bottom