 Android & iPhone
@Circle issues Coinbase masters users: Who earns the money for the stabilization coin?
IOSG Ventures
Just now
Author:Darko @IOSG
Everyone was looking at who issued the stabilizer, but from a business model it was really up to who had access to the distribution channels.
The encryption industry has spent 10 years looking for a product that will be used by people outside the circle. Stabilizing coins is the answer. Over the past year, mainstream financial institutions have finally understood it.
The key changes are not in technology, but in institutional attitudes. The GENIUS Act, which entered into force on 18 July 2025, established for the first time a federal regulatory framework for United States-based stable currency payments. Since then, OCC has promoted or approved the National Trust Bank licence plates of Circle, Ripple and Paxos. In June 2026, Visa, Mastercard and others joined Open Standard, which is composed of more than 140 companies, and launched Open USD. United States dollar tokens have been functioning since 2014, and technology has not suddenly broken. The real “Aha!” moment is when banks and card organizations finally understand what a stable currency can do.
As at 28 September 2026, DefiLlama showed a total market value of approximately $306.6B in stable currencies, of which USDT was about $183.7B, USDC about $75.4B. Compared to the data used in mid-July 2026, the aggregate volume increased slightly, and USDC also increased. The Citi benchmark forecast remains at $1.9T in 2030.
There are two things to see beyond passion.
First, the volume of transactions in the title is significantly overestimated for real use.BCG and Allium estimate that the total amount of stable currency transfers in 2025 was about $62T; after removing robotic transactions, routers and internal transfers, only $4.2T was available, with a real value of $350B-$550B for goods and services. Real payments were one to two orders lower than headline.
Second, supply contractions and high use of innovation can occur simultaneously.In June 2026, the supply of stable currency decreased by $7.7B, the largest single-month decline since 2022, but only 2.4% without anchoring. In the same month, adjusted transfers reached $1.79T, a 63% increase over the same period.
There are three reasons behind this:
Encryption markets reduce risk.
BTC and ETH fall, with spot bitcoin ETF flowing out of more than $4B. Traders will buy off the collateral when they go for leverage, but business wages and operating funds will not disappear simultaneously.
The market should pre-empt the interest-bearing restrictions of the GENIUS Act.
The restrictions will come into effect on 18 January 2027, and some of the funds have been redirected to a monetized national debt that still provides direct revenue. As at 24 September 2026, monetization of US Treasury bonds was about $14.9B, down from around $16B at the end of July.
The speed of currency flows has increased.
Standard Chartered estimates that the stabilization currency is moving about six times a month, twice as much as it was two years ago. The same amount of payment now does not need to sink the same amount of stable currency balance.
Only the first point is that the demand for a stable currency is still affected by the encryption cycle, and it is not necessarily the most important factor.
The third point is of the utmost importance because it does not fully correspond to the interests of the issuer. The income from issuance is roughly equivalent to “silver funds x yield.” The more widespread payments are made, the faster the funds go; the smaller the stable currency balance needed for each dollar to be paid.
Trade collateral is parked there, making money for the issuer on a continuous basis; operating capital is flowing, contributing less to the deposit. If thesis is paid, the issuer will get more use, but not necessarily more from each unit.
The question is therefore no longer whether the stable currency will grow, but rather:
If the stable currency becomes a default transmission of Internet dollars, which layer will keep the profits?
The distribution of the revenue pool and distribution decisions.
Where's the money coming from and who took it?
There are five tiers of players in the stable currency ecology that make money, corresponding to three business models: interest rate on reserves, volume of transactions for money flow charges and SaaS for infrastructure.
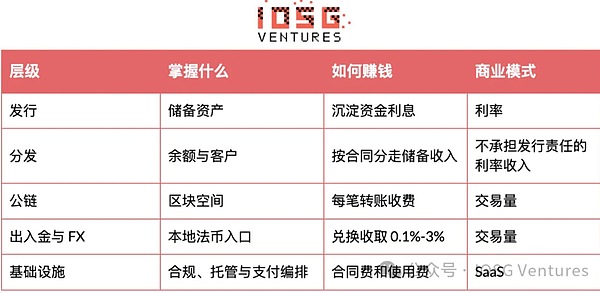
This is the most asymmetrical. The distribution end creates the largest profit pool, and the distribution end decides where the money will stay, but the real public chain responsible for the transfer is the cheapest level in a value bank.
The issuer earns interest, but he doesn't have the full profit.
Circe has been listed and the disclosure is most complete and suitable for analysis.
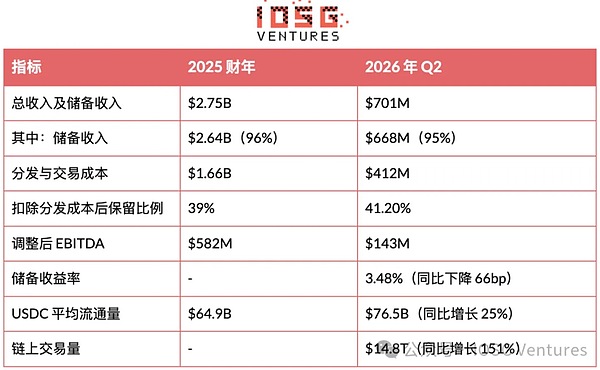
These figures show three things.
Revenue follows the sedimentary funds rather than the amount of payments.
Circle earns interest during the rest of the balance stay, not for the handling costs incurred when the dollar moves. In 2026 Q2, USDC chain trade increased by 151 per cent without directly increasing reserve income.
It is interest rates, not competition, that really hold up income.
The average liquidity of USDC grew by 25%, while reserve revenue increased by only 5%. Reserve yields fell at 66bp, eating most of the increase in balance growth. This is more like the impact of SOFR down, not the share of USDC taken by competitors.
Less than half of the issuers remain.
Circe left 39% after deduction of distribution costs in 2025, and in 2026 Q2 rose to 41.2%. The share taken by the distributor did not continue to rise, but its revenue pool is shrinking as interest rates decline.
Whoever controls the user, he knows the split.
The following four sets of data are more and more deserving of the attention of the issuers.
Circle, get the license plate, Coinbase, or do you take a penny?
Under the 2023 agreement, Coinbase receives most of the reserves generated by USDC within its platform and shares some of the reserves earned outside the platform. Q2 in 2026 paid Coinbase $324.6M for distribution costs; approximately $1.66B was paid to major distributors throughout 2025.
The three-year agreement entered the renewal window in August 2026.
That is the strongest evidence of the full text. Circe was granted federal trust bank licences, payment networks were growing and there were several distribution cooperation cases that gave 90-100% of the reserve earnings to channels. Two months ago, Coinbase joined the Open USD alliance with USDC, which dropped its stock prices by about 17% the same day.
The reason is simple: the customer is in the hands of the distributor. The renewal of a contract also depends primarily on the performance threshold, which does not amount to a re-pricing initiative by the issuer.
In 2026, the average USDC balance in the Q2, Coinbase product reached an all-time high of $20B, accounting for over 30% of USDC traffic at the end of the season. Nearly one third of the revenue base of Circle is concentrated on a single rival platform, while the next full extension window will wait until 2029.
Hyperliquid: Wanting to pay your own money to eat interest, then going back to USDC.
In September 2025, Hyperliquid launched USDH in the hope that billions of dollars from USDC’s equivalent reserves on the platform would be left to itself. The USDH maximum size was only about $21M and ceased operations on 20 June 2026.
Follow-up arrangements are more interesting. Hyperliquid has about $6B USDC. Coinbase counts it to the balance of the platform, earns the corresponding reserve income and returns approximately 90 per cent to Hyperliquid. Why is Coinbase in the middle instead of Circle doing it directly? Because Coinbase has a concessionable channel profit. By identifying the balance as funds within the Platform, Coinbase obtains a higher percentage of proceeds and then there is still room for return to Hyperliquid. The economic interests of Circle are largely fixed in both cases and have been targeted for a further three years after renewal.
The USDG doesn't make money by issuing it, but by giving it to the channel.
Paxos issues Global Dollar, a network of partners such as Robinhod, Kraken, Galaxy and Mastercard. Partners can retain the vast majority of their reserve earnings; up to 100% if the balance remains on their own platform.
This model is self-enhanced. Robinhod Chain came online on July 1, 2026, setting the USDG as the only original stabilization currency, issuing $178M in the first week and supporting 7% of the Earn product. Channels that leave profits will naturally channel their chains, voucher businesses, and 27 million accounts to stable currencies that are most willing to pay.
Open USD: Group of over 140 companies that trade in stabilization currency as a channel
Open USD was launched in June 2026, with more than 140 participants, including Visa, Mastercard and Coinbase. After deducting management fees, it distributes the proceeds of the reserve to distribution channels. USDG certification channels can take the proceeds through contracts; Open USD puts this arrangement directly into product design and takes on large card organizations.
Coinbase completes its renewal as the largest distributioner of USDC, while joining Open USD. Its disclosure shows that in the first half of 2026, USDC and Coinbase together accounted for 79% of stable currency transactions, up from 55% in 2025.
Interest rate dropped by 300bp, distribution profits evaporated almost 80%.
The issuer ' s income can be simplified as: the deposit fund x rate of return, less the contractual channel share and less relatively fixed operating costs.
Assuming that a distributor has $100B deposited funds, 50% of the proceeds are allocated to channels at an annual operating cost of $600M:
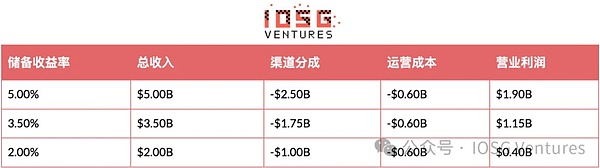
If the deposit remains constant, the return drops by 300bp and wipes out about 79% of the business profits. To continue to earn $1.9B at a rate of 2%, the deposit must increase to around $250B. That is to say, if the scale increases by 150%, the profit will only return to its original point of origin.
This is no longer a hypothesis. The actual reserve return for Q2 in 2026 was 3.48 per cent, just near the second line. 50 per cent of the channels were divided into assumptions that even conservative: $701M of total revenue for the current season and $412M of distribution, trade and other costs.
Of course, Circe didn't do anything.
At the end of the quarter, the annualized trade volume of Circle Payments Network reached $14.7B, an increase of 76 per cent; it had risen to $23B as at 31 July. The company moved its annual non-reserve income guidelines upwards to $310M-$330M. Of these, $242M came from one-time token pre-sale and was not sustainable revenue. The payment network had yet to start charging fees, so it really needed to focus on tariffs rather than transaction volumes.
Circe is also expanding downstream. While writing in the original language, Arc plans to go online on September 16th. As of the date of this update, the Arc Public Main Network has been on line with over 100 institutions and ecological builders participating in the first day, and BlackRock, DTCC, ICE, Mastercard, Standard Chartered and Visa are working or participating in validation and integration. Circe is purchasing the location of the settlement layer with sufficient and sufficient deposit income.
Tether looks like an exception, but data from 2026 Q2 indicates that direct analogies are misleading. Tether reported operating profits of approximately $1.5B, USDT issues about $184.6B, holding some $115B United States Treasury debt, and no large channel share like that of Circle. However, the company ' s emphasis on operating profits does not include changes in the market value of its own gold and bitcoin, which have fallen significantly during the current season. The excess reserve was reduced from $8.23B to $4.11B. Supply has increased, while the buffer has been halved by changes in asset prices.
The same accounting calculus magnifies the profits that are often quoted from 2024. Of the $13B profit reported at one time, approximately $5B comes from unrealized gains. By removing both positive and negative market-rate fluctuations, Tether is more like a quarterly $1B-$1.5B bond differential: large volume, interest rate sensitivity, and exposure to balance sheet risks that the regulated issuer would not normally be able to bear.
The true dividing line is not “supervised” and “offshore”, but has its own distribution and lease distribution. The Circle Rents Channel, the terms of which were locked up until 2029; Tether built a network before the regulatory era.Banks and payment companies usually leave much more than 41 per cent of their profits if they have direct control over their customers.
The chain runs faster, and usually only makes a small gain.
Transfers on Solana or Base often cost less than a cent. Transfer fees are almost negligible compared to the interest generated by a year's deposit of a dollar in reserve.
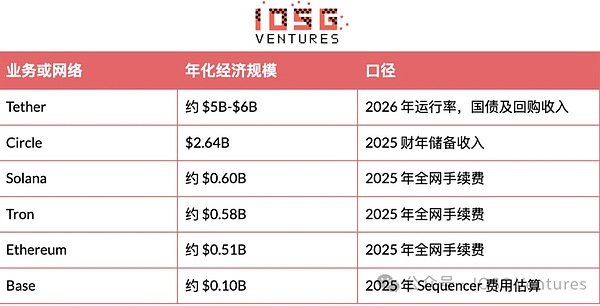
These figures can only be used for directional comparisons, and the different calibrations of data are not consistent, and Tron is particularly vulnerable to statistical methods.
Tron is the most instructive exception. BCG estimates that in 2025 Tron processed real economic stabilization payments of approximately $235B-375B, which exceeded other public chains. The reason is not throughput, but some cross-border routes have become standard around Tron: exchange support, wallet integration, deep USDT mobility and long-established user habits.
Even so, Tron does not have a customer. The access service brings the user in, the wallet provides an interface, and Tether offers the dollar. Tron is the clearing track for this channel, not the distributor.
Neutral block space is difficult to achieve high profits, because the public chain has been competing for cheaper people. Orbital pricing is only possible when mobility and usage practices make it difficult for users to leave.
The biggest winner is hidden under the chain: US Treasury Department.
Under the 2023 agreement, Coinbase receives most of the reserves generated by USDC within its platform and shares some of the reserves earned outside the platform. Q2 in 2026 paid Coinbase $324.6M for distribution costs; approximately $1.66B was paid to major distributors throughout 2025.
The three-year agreement entered the renewal window in August 2026.
That is the strongest evidence of the full text. Circe was granted federal trust bank licences, payment networks were growing and there were several distribution cooperation cases that gave 90-100% of the reserve earnings to channels. Two months ago, Coinbase joined the Open USD alliance with USDC, which dropped its stock prices by about 17% the same day.
The reason is simple: the customer is in the hands of the distributor. The renewal of a contract also depends primarily on the performance threshold, which does not amount to a re-pricing initiative by the issuer.
In 2026, the average USDC balance in the Q2, Coinbase product reached an all-time high of $20B, accounting for over 30% of USDC traffic at the end of the season. Nearly one third of the revenue base of Circle is concentrated on a single rival platform, while the next full extension window will wait until 2029.
All those who have been involved in this fight are actually fighting for the same pool of returns: interest on reserve assets. Where does interest come from? The answer usually does not appear in a stable currency value chain map.
The GENIUS Act requires the issuer to hold cash, or United States Treasury debt for a period not exceeding 93 days. It not only regulates stabilization currency but also creates short-term demand for US Treasury debt in legal form.
At the end of Q2 in 2026, Tether held approximately $115B United States Treasury debt, claiming to be the largest non-sovereign holder. The majority of the reserves of about $79B were placed in BlackRock-managed funds. The IMF noted that the combined United States Treasury debt of both companies exceeded Saudi Arabia.
Some 99.8% of the stable currency supply is denominated in United States dollars, and therefore growth in the stable currency will generate T-bill demand regardless of the level at which it is ultimately taken. Standard Chartered envisages that the stabilization currency would reach $2T in 2028, corresponding to a new purchase of US Treasury debt of about $1T at most. Such buyers hardly existed five years ago and did not require a term premium.
There are, however, two additional restrictions. First, the money market fund industry, which is still small relative to about $7T, is a growing marginal buyer and does not dominate. Secondly, the impact of financial inflows and disbursements on rates of return is asymmetric. The BIS study found that an inflow of $3.5B could reduce the rate of return on the 3-month national debt by about 2-2.5 bp; The same size of outflows pushes up 6-8bp. Redemption hit no-risk interest rates approximately three times as high as requisitions. So June $7.7B supply contraction is not just an emotional indicator.
A real steady business, hidden in access money, FX and compliance.
Access grant with FX.
The BCG estimates that exchange access rates are about 0.1-1%, professional service providers are 1-3%, and encryption ATMs can be as high as 7%. Emerging markets also have higher FX margins for cross-border routes. These are the widest trading profits in the whole value chain, and are concentrated where demand is most rigid: getting the dollar.
Compliance, hosting and payment organization.
List screening, transaction monitoring, key management, hosting, reserve services, and auditable reports are mostly required. It is less bright than the return on reserves, but it is more stable: long contracts, high conversion costs, and interest rates of 5 per cent, and less dependent on a certain channel for renewal.
The floor may not take the largest profit pool, but it can be charged regardless of the last stable currency.
After the issuer can't pay, the channel is more valuable.
The GENIUS Act prohibits the issuer from paying interest directly solely on account of the user ' s currency, but does not explicitly prohibit an independent exchange or purse from subsidizing its own share of the reserve income.
The intention of the legislation is to keep stable currency as a tool for payment, rather than becoming a substitute for deposits. The actual market effects are different: when the distributor cannot compete with the balance from the proceeds, competition will shift to a channel that controls users. The distributor pays the distributor and then decides whether or not to give a portion of it to the user.
So the interest-rate ban protects channel profits. USDG and Open USD are designed to use this space.
This advantage is also controversial. The banking community wants to extend restrictions to third-party incentives, and the partial market structure bill of 2026 seeks to limit passive earnings more broadly.
Banks also face choices: they issue and bear the cost of hosting and reserve money, join coalitions or watch deposits flow. My benchmark is that most announced bank stability currency eventually becomes union products or infrastructure cooperation. The distribution has a clear scale effect, and single banks rarely have sufficiently large distribution networks to build liquidity independently.
Conclusion: a stable currency will be commodified and the entrance won't.
Visa doesn't issue cards, don't lend loans, or collect intermenge directly; the work is done by banks.
The production of payment instruments does not amount to controlling profits. The value eventually flows to the party in control of the scarce control points: receiving networks, distribution channels, mobility, or customer relationships.
The stabilization currency is rapidly rebuilding the structure. Three conclusions can be drawn from this.
Releases will be standardized over time.
The GENIUS Act does not make distribution easy, approvals, liquidity, redeeming infrastructure and trust remain the thresholds, and Circe's federal licence plates do have value. However, regulation requires the issuer to hold similar reserve assets and disclosure rules will converge, with each regulated dollar-stabilizing undertaking being the same. The difference will shift over the token. The Circe license came before the renewal window and did not change Coinbase's terms.
The downward trend in interest rates would reduce the profits of the deposit funds and have already begun.
The reserve rate of return has fallen by 66bp, allowing 25% of average liquidity growth to be replaced by 5% of reserve income. Any distribution model measured at 5% interest rates should run 2% again. Circulation growth can offset interest-rate reductions, but it must run before channel sharing and fixed cost erodes profits. What is more difficult is that the minimum balance needed to support each dollar transaction.
The distribution channel has bargaining power.
Coinbase's renewal was the most informative stable currency contract event in 2026, and the information came from “nothing changes”. Circe enters the renewal window with federal plates, an increasing payment network and open comparable cases of 90-100 per cent transfer of proceeds to channels; Coinbase has more than 30 per cent of the USDC balance, joined the competition union and had no obligation to renegotiate. Ultimately, the agreement continues in its original terms until 2029.
The asset configurors can be screened by:
Pressure tests of pure distribution patterns are also conducted using lower yields and higher channels.
The automatic renewal mechanism itself is usually more conducive to channels.
A split between one-time income and sustainable income. Currency sales and online incentives would be a boon to the performance of the transition period, with what really matters is the corresponding rate of payment.
The focus is on companies that have access to the entrance and specific payment routes, especially in emerging markets where the United States dollar is scarce and FX points are much wider.
Compliance, hosting and trading infrastructure are least sensitive to interest rates but still need to be factored into regulatory and periodic risks.
Don't treat trade volumes as income. USDC handles $14.8T for a quarter, but still earns mostly from static balances.
If this is truly a currency “Aha!” moment, the inspiration from AI is not that underlying models are bound to be commodified, but rather that capacity spreads quickly, prices are pushed down, and bargaining power eventually flows to scarce distributional capacity and customer relations.
Stable currencies themselves may become more and more fungible, but the path by which users acquire, hold and spend them is not.
 0

Statement: The present paper was written by the author of the gold-based financial estate, whose views are expressed only on behalf of the author and in no way represents the gold-based financial system which shares his view or confirms his description.
This information is not a financial investment proposal.
 Save


- @Circle issues Coinbase masters users: Who earns the money for the stabilization coin?
- Bian's Shanche currency knockout: 294 Delist's survival rule
- HIP-3: Cost-effective tickets to the moat that can't be bought
- In 2021, Robinhod turned off AMC's buy-in key.
- Border bet: Why is the best investment in encryption born in Bear City?
24-hour text
 After $387.5 million was stolen, Bitget and thorchain got in a fight.
Conflux Tree Map blockchain
 How did the harvest line at the Meme Factory come out of the water, Robinwood Chain?
Chain catcher ChainCatcher
 Bitcoin goes into shock and waits for a new catalyst?
Knight of the Zone Chain.
 US SEC Committee member: Is the more regulatory data collection the better?
Asia-Pacific Future Study
- Seeking coverage
- Jinse Finance AppiOS & Android
- Community
Telegram - Feedback
- Back to Top
- Back to Bottom