 Android & iPhone
Professor Li Guo Kwon, Director of the Institute of Global Finance Technology and Technology: Where will the financial system go after the Stable Currency, the RWA and AI?
Jinse Finance
2026/09/23 16:33 100K
On 23 September 2026, the International Week of the Shanghai blockchain and the Twelfth Global Summit of the blockchain were inaugurated, and Professor Li Guo Kwon, Director of the Global School of Finance and Technology, was honoured to be invited by the Gold Bank.
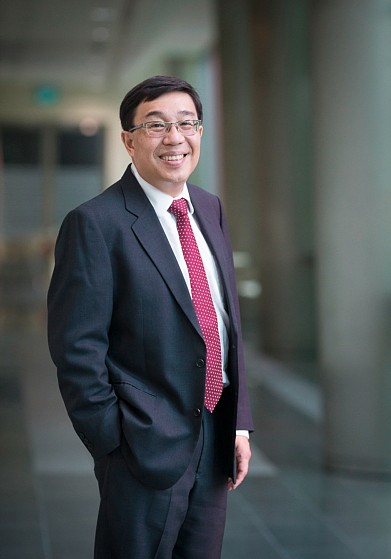
Here are some of the interviews that took place.
The changes in the industry over the past decade or so are not a break-up of each other’s hotspots, but rather a continuous evolution of finance from digitalization, programmability, to intellectualization and institutionalization. Stabilizing currencies, monetized assets, and artificial intelligence will accelerate the rebuilding of financial infrastructure, but long-term values still depend on real demand, legal rights, market liquidity, risk management, and expertise.
What can be left behind is not necessarily the fastest-growing project, but rather an infrastructure that can solve real problems, generate sustainable income and meet regulatory and social trust requirements.
In the future, global regulation will lead to “convergence of principles and division of paths.” But there will be no identical regimes everywhere. The United States relies more on securities law, commodity law, and division of competences among market institutions; Hong Kong follows a path of licensing and progressive product liberalization; and Singapore places greater emphasis on activity regulation, payment security, anti-money laundering, and institutional asset monetization.
Stabilized coins do not simply destroy banks. They are more likely to force banks to change their roles: from a courier of payment information to a regulated money, liquidity, trust, identity, compliance and balance sheet provider. The future competition is not about “bank versus stability”, but who can connect deposits, stable currency, tokenized deposits and central bank currencies into secure, compliant and interoperable payment networks.
Traditional markets are absorbing three features of digital finance: longer or even consecutive transaction times; programmability of assets, trading rules and clearing instruments; and the gradual move away from separation to closer atomization of transactions and settlements. Digital finance will also absorb the institutional capacity of traditional finance, including regulated trusteeship, liquidation and asset isolation, market surveillance, information disclosure and investor protection, as well as governance, recourse and correction mechanisms in case of error, fraud or systemic accident.
Policy prostheses by themselves do not prove that a round of long-term cattle markets has taken shape. I will look at four indicators: whether the funds come from short-term leverage and emotional trading or from long-term configuration; whether the increase is accompanied by growth in real use, trade income, settlement demand and development activities; whether the price of currency matches the economic value that the project can create or share; and whether the market rise depends on a few high-leverage platforms, revolving finance or related party transactions.
Gold: You've been studying block chains for more than 10 years. In the last decade, industry has experienced several races, ranging from DeFi, NFT, Meme to stabilization currency, RWA, AI, etc. Do you think this is the same technology cycle or different stages of the same financial digital revolution?
Professor Li Guo Quan,I think both terms are valid, but on a longer time scale they are more like different experimental stages of the same financial digital revolution.
As early as 2015, I observed the change using “6Ds”: Digitalization (digitization), Disintermedialization, Democratization and Inclusion, Decentralisation (decentrization), Diminishing Oneself (self-diminishing), and ultimately Data Security and Privacy. These six directions are not six divisive slogans, but a step-by-step evolutionary path: when financial, identity and social activities are fully digitized, how power is decentralized, how individuals retain autonomy, and how data are protected are at the heart of the system.
The first stage addresses “how digital assets exist.” Bitcoin proves that in the absence of a central book, it is possible to shift the value of numbers and points-to-points. The second phase deals with “how digital assets are programmed.” The inclusion of trading, borrowing, making markets, derivatives and governance in the programming process with Taifa, smart contracts and DeFi has further moved finance from electronic to programmable.
NFTs and Meme do two other kinds of experiments. NFTs test digital property, identity, community and cultural assets; Meme tests attention, community mobilization, and network effects. They are highly speculative, but they also show that in the digital economy, attention can quickly be translated into liquidity and asset prices.
The third stage now is the connection between digital finance and real economy. Stabilizing currencies solve the problem of payment and pricing instruments along the chain; RWA brings bonds, funds, deposits, receivables and other realistic rights to programmable networks; and AI begins to be involved in analysis, transactions, compliance and even self-payment.
As AI merges with Web3, we are entering the most valuable and critical phase of this evolution. AI ' s capabilities are derived from data, but the stronger AI, the greater the risk of data abuse, concentration of power, identity manipulation and algorithms not being transparent. Thus, the ultimate competition is not just modelling capacity but data security, credibility and institutional trust. Decentrization of hardware and software, privacy protection, verifiable computing and auditable governance will form the basis for confidence-building. In a sense, it also brings the industry back to its original motivation: to use code science to protect individual rights, privacy and freedoms rather than simply create more tradable tokens.
So I do not think that these tracks are isolated from each other. Together, they drive three shifts: from the digitization of assets to the digitization of rights and rules; from manual execution to smart contracts and AI agency enforcement; and from closed books in a single institution to inter-institutional, cross-platform and cross-border synergetic books.
However, every wave of technology has to be accompanied by bubbles. We have to distinguish between technological feasibility, commercial sustainability and institutional acceptability. What can stay is not necessarily the fastest-growing project, but rather infrastructure that can solve real problems, generate sustainable income and meet regulatory and social trust requirements.
The Global Institute of Finance Science and Technology (GFI) has been emphasizing that financial technology cannot only train people who know technology, but also those who know regulation, as well as cross-cutting talent capable of understanding finance, science, technology, governance, and ethics at the same time. Here is the meaning of the CFtP certification system: helping practitioners establish common standards of professional language and responsibility, not just learning how to issue a Token or chase the next hot track.
Gold money: In mid-September 2026, the US SEC granted temporary and conditional “innovation exemptions.” The US, Hong Kong, etc. are pushing forward with encryption asset regulation. Do you think that global regulation will gradually converge in the future, or will it retain its own characteristics?
Professor Li Guo Quan,First of all, it needs to be made clear that the “innovation exemption” granted by the US SEC this time is not a complete relaxation of the entire encrypted market. It allows mainly eligible places for exchange of tokenized securities, using automated markets and liquidity pools in licensed environments, to trade in dollarized United States-listed shares.
It is a temporary, conditional arrangement for five years. The place of the transaction and the provider of liquidity are exempted from the definition of part of the “exchange” and “trading” only after the conditions have been met. Currencyized shares must also retain the same economic benefits as traditional stocks, dividends, voting rights, and liquidations.
The most noteworthy of this arrangement is not just the words “currencyized shares”, but rather the explicit reference in regulatory documents to automatic market business, namely AMM, and the liquidity pool. This is an important institutional signal. The chaining of assets does not automatically create a market; Without sustained liquidity, reliable marketing and orderly exit mechanisms, prices do not adequately reflect the value of financial assets, nor do they remain at the technical level. AMM brings the market formation mechanisms of digital finance into regulated securities markets, but at the same time must address price manipulation, liquidity depletion, conflicts of interest, prognosis and smart contract risks.
Future global regulation will be “convergence of principles, routing” which will include: the same functions, the same risks, and close supervision in principle; a universal focus on asset reserves, customer asset segregation, foreclosures, market manipulation, conflicts of interest, cybersecurity and AML/CFT; a shift in regulatory focus from “token's name” to who controls it, who is responsible, where assets are located, what rights investors have and how to pursue them when problems arise.
The US relies more on securities law, commodity law, and the division of competences among market institutions; Hong Kong follows a path of licensing platforms and product liberalization; Singapore places greater emphasis on activity regulation, payment security, money-laundering, and institutional asset monetization.
So, the future will not be a set of globally harmonized regulations, but rather a minimum standard that can be identified. What really needs to be promoted is regulatory interoperability, including common data standards, travel rules, storage certificates, identification documents, audit interfaces and cross-border law enforcement cooperation.
The role of the GFI is to bring regulators, financial institutions, technology firms and academia from different jurisdictions to the same platform to discuss common standards. CFtP helps practitioners understand the regulatory logic of different markets and avoid copying business models allowed in one country into another without judgement.
Gold money: Stabilizing currency has become one of the most popular areas in global financial technology. What is the greatest value of a stable currency?
Professor Li Guo Quan,The best value of a stable currency is not price stability per se, but it transforms the currency into a clearing tool that can be used in Internet and smart contracts.
Traditional cross-border payments usually involve multiple correspondent banks, different business times, pre-positioned liquidity, and multilayered reconciliations. Stabilizing currencies allow funds to be transferred in near real-time environments and are directly linked to digital assets, electronic bills of lading, supply chain data and smart contracts.
It may result in four changes: payments are settled from the transmission of information to the simultaneous transfer of information and value; settlement time is reduced from days to minutes or even seconds; enterprises can include payment terms such as goods confirmation, invoice validation or compliance inspection into smart contracts; it also provides a basis for machine payments and AI agency payments.
Its most important social and economic contribution is to reduce the cost of cross-border remittances, trade receipts, and liquidity for MSMEs. Today, large firms can use global banking networks and professional financial management to lower costs, but MSMEs and small remittance users tend to bear higher fixed costs, longer time to arrive, and more transparent exchange rate differentials.
When the currency of stability became programmable, its contribution was no longer limited to payment. Payment terms, collateral, repayment order, interest allocation and risk limits can be embedded in the transaction process to improve lending, trade finance and capital market operations. It could help to create smaller, more timely and transparent financing instruments that would allow enterprises that traditionally had difficulty accessing capital markets to access new lending channels. This is consistent with the long-standing goals of the World Bank and the International Monetary Fund to reduce the cost of cross-border remittances, financial inclusion, financial stability and orderly regulation. It is essential to embed regulatory rules into the system so that compliance can be validated, results audited, authority withdrawn and financial order maintained while costs are reduced.
But a stable currency does not simply destroy banks. It is more likely to force banks to change their role: from a courier of payment information to a provider of regulated money, liquidity, trusteeship, identity, compliance and balance sheets.
Banks still have the capacity to stabilize money issuers and purely technological platforms that cannot be completely replaced, including customer scrutiny, credit creation, foreign exchange liquidity, fraud management, sanctions screening, and legal recourse. The future competition is not about “bank versus stability”, but about who can connect deposits, securitized currency, tokenized deposits, and central bank currencies into secure, compliant and interoperable payment networks.
The greatest risks include reserve asset quality, foreclosure run-off, currency substitution, dollarization, issuer concentration, cyberattacks, and anonymous cross-border movements. Thus, the development of stabilization currencies must go hand in hand with reserve regulation, foreclosure, liquidity management, and AML/CFT requirements.
Gold finance: In recent years, traditional financial infrastructures, including NASDAQ and CME, have been exploring longer trading times, digital asset transactions, and block-chain technologies. How do you think traditional financial markets and digital financial systems integrate in the future?
Professor Li Guo Quan,The future will not be completely replaced by a blockchain, nor will it end up being absorbed entirely by a traditional one. I prefer to interpret it as “two-way integration”.
CME has already started its 24x7 transactions in cryptocurrency futures and options at the end of May 2026, but still maintains the necessary systems maintenance windows and continues to operate within a regulated liquidation and reporting system. The US SEC’s innovative exemption further allows for specific monetization of United States stocks on licensed chains, through automatic marketing and liquidity pools.
Traditional markets are absorbing three features of digital finance: longer or even consecutive transaction times; programmability of assets, trading rules and clearing instruments; and the gradual move away from separation to closer atomization of transactions and settlements. Digital finance will also absorb the institutional capacity of traditional finance, including regulated trusteeship, liquidation and asset isolation, market surveillance, information disclosure and investor protection, as well as governance, recourse and correction mechanisms in case of error, fraud or systemic accident.
It may end up not as a completely open and anonymous blockchain, but rather as a multi-layered structure: the bottom can use public chains, licensing chains or shared books; the upper tiers provide identity, hosting, trading, mobility, and compliance services by regulated institutions. Privacy techniques and zero knowledge prove to reduce unnecessary data exposure, but cannot be used as a tool for avoiding regulation.
The real difficulty is not to cast securities into Token, but to deal with company actions, voting rights, dividends, taxation, bankruptcy isolation, final settlement, cross-chain risk and legal ownership. If the chain does not match the right under the chain, so-called monetization is just a layer of digital packaging.
Markets are also expected to become more important in an AI-Web3-integrated world. (b) The forecast market should not be understood as a mere instrument of investment, provided that the law permits, holds and is regulated; It can be a tool for risk hedging, event insurance, information aggregation and credibility formation. Market prices bring decentralized judgement together into a visible signal that helps enterprises, investors and regulators to assess policy, credit, supply chain and technology risks. When integrated with AI, it can also be used to test model judgements, constrain overconfidence algorithms and preserve an external validation mechanism for human judgement. Of course, the risks of manipulation, insider information, conflict of interest and illegal gambling must be protected simultaneously.
What financial institutions need in the future is not just people who can operate traditional trading systems or prepare smart contracts, but complex talent that can understand market microstructures, block chains, AI, regulation, and ethics. GFIs and CFtP can establish a common professional base between traditional finance and digital finance.
Gold: Do you think this round of an increase in crypto assets driven by US regulatory policy is a short-term scenario or a sign of the opening of a new round of cattle? What tracks do you value?
Professor Li Guo Quan,Regulatory policies can improve market expectations, reduce institutional uncertainty, and attract more institutional capital. But good policy outcomes by themselves do not prove that a long-term round of cattle markets has taken place.
I will look at four indicators: whether the funds come from short-term leverage and emotional trading or long-term allocation; whether the increase is accompanied by real use, transaction revenue, settlement demand and growth in development activities; whether the price of the currency matches the economic value that the project can create or share; and whether the market rise depends on a few highly leveraged platforms, revolving finance or related party transactions.
Therefore, I will not simply predict that the cattle market has begun, nor will I consider all crypto assets to be beneficial because of regulatory improvements. Regulatory clarity usually drives industry differentiation rather than a general appreciation of all projects. Projects with strong compliance capacity, clear use and more realistic cash flows benefit; projects that lack transparency, depend on speculation and fail to meet AML/CFT requirements are likely to be marginalized.
If we start with long-term industrial development rather than short-term currency prices, I believe there are four basic capabilities that cannot be absent: a stable currency provides programmable payments and settlements; (a) The forecast market provides information aggregates, risk hedges, insurance and reputation signals, subject to legal authorization and regulation; (b) Market traders and AMM to provide liquidity and price discovery; Privacy protection preserves individual rights, business secrets and institutional trust. They also have long-term value in the surrounding industries of hosting, identity, auditing, prophecies, network security, cross-chain interoperability, compliance technology and zero knowledge certification.
These four capacities are particularly important in a world where AI is extensively involved in decision-making, trading and value transfer. Stabilizing currency to enable the flow of value; Forecasting markets helps to validate collective judgement; Market mechanisms to enable prices to reflect information; Privacy and decentrization prevent excessive concentration of data and power. Together, they form the economic and institutional basis for checks and balances in AI, enabling us to check, discipline and correct it, preventing it from moving in the direction of anti-humanity, social manipulation or undermining the real economy. The most valuable digital infrastructure in the future is not just to make AI stronger, but to ensure that it still serves people.
I would be very cautious about relying solely on narratives, celebrity effects or community-made assets. Technology is not as useful as a token; Increased use of the network does not necessarily mean that value will be attributed to the token holder. What is really of concern is not the short-term most rapid increase in money, but the infrastructure that can reduce the cost of financial transactions, expand credible participation and remain secure and compliant under market pressure. It is not the responsibility of educational institutions to teach people to follow suit, but to help professionals identify technical values, market risks and institutional boundaries.
Note: The content on market trends and track judgements is a policy and industry analysis and does not constitute an investment recommendation.
 0

Declaration: This is a gold original, the copyright is a gold one and cannot be reproduced without authorization. A copy of this article must be downloaded from an agreed-upon medium with the indication "Source: Gold Book", for which the offender will be held liable under the law.
This information is not a financial investment proposal.
 Save


- Pantera's latest status report on monetization.
- What game is AAVE playing next?
- US SEC issues an update of the crypto asset FAQ to add a new issuer's currency buyback definition
- QNT surged over 300% a week, currency deposits infiltrated the core of the United States banking system?
- Vitalik's latest post: The Ether Workshop will become a password-based world computer.
24-hour text
 Eight hidden details of Anthropic's book.
GenAI Summit
 Bitcoin goes into shock and waits for a new catalyst?
Knight of the Zone Chain.
 How did the harvest line at the Meme Factory come out of the water, Robinwood Chain?
Chain catcher ChainCatcher
- Seeking coverage
- Jinse Finance AppiOS & Android
- Community
Telegram - Feedback
- Back to Top
- Back to Bottom
Listen to Jun's words and read a book for 10 years. I wish I could have seen it earlier.